Almost every first-time buyer mistake I see in Florida happens before anybody looks at a house. Shopping without a lender strategy. Budgeting off the sticker price. Forgetting that insurance and community assessments are part of the payment. Waiting too long to dig into the property itself.
Looking at listings is the fun part, and I’d never take that away from you. But after walking a lot of buyers through this across Tampa Bay and Southshore, I can tell you the ones who end up happiest knew their real monthly payment, their cash to close, and their due-diligence plan before they ever wrote an offer.
1. Starting the home search before understanding the financing
Scrolling through homes can help you learn the market, but serious touring should begin with a realistic financing conversation. A lender can review income, credit, debts, available funds, and loan options. That information helps establish a payment and price range before emotions become attached to a property.
A preapproval isn’t a promise that every home or loan scenario will qualify. Taxes, insurance, HOA dues, CDD assessments, property condition, appraisal results, and loan requirements can change the numbers. Ask the lender to update the estimate when the target property changes.
2. Shopping by purchase price instead of total payment
Two homes with the same price can produce very different monthly costs. Buyers should compare principal and interest together with projected property taxes, homeowners insurance, mortgage insurance when applicable, flood insurance when applicable, HOA dues, CDD assessments, and other recurring housing expenses.
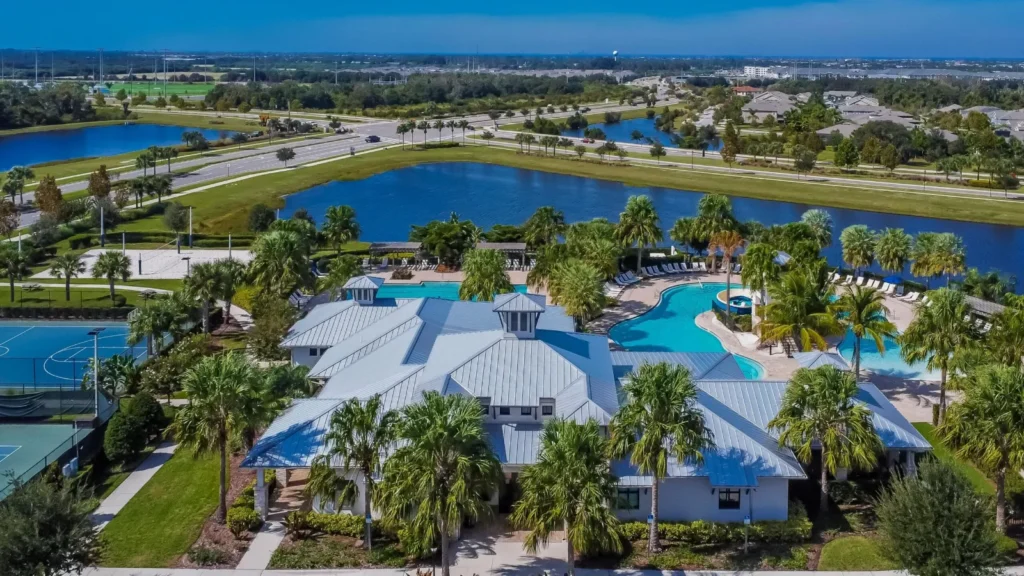
This is especially important in Southshore Florida. A newer master-planned home may include HOA and CDD costs. A canal-front home may have different flood, insurance, seawall, dock, and maintenance considerations. A condominium may include substantial services in its association fee, but the buyer still needs to review the association’s financial condition, insurance responsibilities, and potential assessments.
3. Using every available dollar for the down payment
The down payment is only one part of the cash needed to buy. Closing costs, prepaid taxes and insurance, inspections, appraisal costs, moving expenses, utility deposits, immediate repairs, and basic home needs can require additional funds.
The Consumer Financial Protection Bureau explains that closing costs commonly range from 2 to 5 percent of the purchase price, excluding the down payment, although the actual amount depends on the loan, property, lender, location, and transaction. A lender’s Loan Estimate provides the property-specific projection.
Keeping a reasonable reserve after closing can be more valuable than stretching to the absolute maximum down payment. Ask the lender to compare multiple down-payment scenarios and explain the effect on the rate, mortgage insurance, cash to close, and monthly payment.
4. Treating the lender’s maximum as the buyer’s budget
A loan approval is based on lending guidelines. It doesn’t know how much you want to save, travel, invest, spend on childcare, maintain a boat, or keep available for emergencies. The right housing budget should work with your life, not merely fit a qualification formula.
Choose a monthly amount that remains comfortable after including utilities, routine maintenance, and realistic lifestyle expenses. Then ask the lender what price range supports that payment under current assumptions.
5. Searching for the perfect house instead of the right fit
First-time buyers sometimes combine every favorite feature from every house they’ve seen into one impossible target. A better approach separates true needs from preferences.
- Non-negotiables: Items the home must have for safety, function, accessibility, location, or household needs.
- Strong preferences: Features that add meaningful value but may have workable alternatives.
- Cosmetic wishes: Paint, fixtures, landscaping, and finishes that may be changed later.
Flexibility doesn’t mean ignoring important priorities. It means recognizing that location, lot, layout, and structural limitations are usually harder to change than cosmetic finishes.
6. Falling in love with the home but ignoring the location
You can renovate a kitchen. You can’t move the lot. Evaluate the commute, traffic patterns, nearby services, planned development, community rules, noise, access routes, and daily routine.
Visit the area at different times when practical. A neighborhood can feel different during weekday traffic, evenings, and weekends. Buyers should conduct their own research on schools, public services, crime information, and other personal priorities through appropriate official sources.
7. Waiting too long to investigate Florida insurance
Insurance can materially affect affordability and loan approval. Request quotes early enough to understand the likely premium, deductibles, coverage limitations, wind requirements, roof considerations, prior claims information when available, and whether flood insurance is required or advisable.
For homes west of US 41 in Apollo Beach and nearby waterfront areas, flood-zone and elevation due diligence should be expected even though the official FEMA zone and property-specific facts must always be verified. An elevation certificate and the finished-floor elevation may be important to the insurance analysis.
8. Confusing an inspection with a pass-or-fail test
A home inspection is a decision tool. It helps the buyer understand the property’s visible condition and identify areas that may require additional evaluation. The findings should be considered with the contract, repair priorities, available reserves, insurance requirements, and the buyer’s tolerance for future work.
Specialized inspections or evaluations may be appropriate depending on the property. Florida buyers may need to consider items such as roof condition, plumbing, electrical systems, HVAC, pool equipment, seawalls, docks, boat lifts, elevation, flood history, permits, septic systems, wells, termites, or condominium and association documents.
9. Making financial changes during underwriting
The lender may verify financial information again before closing. Buyers should speak with the lender before opening or closing credit accounts, financing furniture or a vehicle, changing jobs, moving money between accounts, making large deposits, or taking on new debt.
Even a purchase that appears affordable can affect qualification or create documentation requirements. Keep financial records organized and respond promptly to lender requests.
10. Accepting one loan option without comparing the details
Rate matters, but it isn’t the only loan cost. Compare the interest rate, annual percentage rate, points, lender credits, mortgage insurance, estimated cash to close, projected payment, rate-lock terms, and loan features.
The Loan Estimate is a standardized form designed to make comparisons easier. Review it carefully and ask questions about anything that differs from expectations. A low advertised rate may be tied to points, a particular down payment, a short lock period, or other conditions.
11. Focusing only on the offer price
A strong offer is a complete package. Price is important, but so are financing strength, deposit structure, inspection terms, appraisal risk, requested concessions, closing date, occupancy needs, and the buyer’s ability to perform.
The best strategy depends on the property and current competition. In a slower market, buyers may have room to negotiate repairs, credits, or seller contributions. A well-positioned home can still attract multiple buyers. Local market evidence should guide the offer instead of a generic rule.
12. Choosing guidance based only on who opens the door
A buyer’s representative should do more than schedule showings. The job includes helping the buyer interpret local market data, evaluate property-specific risks, structure an offer, coordinate due diligence, communicate with the lender and title company, and keep the transaction moving toward closing.
For Southshore and waterfront buyers, local experience is especially valuable. Canal routes, bridge clearance, water depth, seawalls, docks, boat lifts, flood exposure, CDD infrastructure, HOA rules, and insurance considerations can make two nearby homes very different purchases.
A first-time Florida homebuyer checklist
- Choose a comfortable monthly housing budget.
- Meet with one or more reputable lenders and compare loan options.
- Estimate down payment, closing costs, and the reserve you want after closing.
- Define location needs, non-negotiables, and flexible preferences.
- Tour homes using total ownership cost, not price alone.
- Request early insurance guidance for serious candidates.
- Review HOA, condominium, and CDD information when applicable.
- Build inspection and specialized due diligence around the specific property.
- Review the Loan Estimate and ask whether the rate is locked.
- Avoid financial changes without first speaking with the lender.
- Read the Closing Disclosure and compare it with the most recent Loan Estimate.
- Keep a post-closing reserve for moving, maintenance, and surprises.
First-time Florida homebuyer FAQ
Do I need 20 percent down to buy my first home?
No. Some loan programs permit lower down payments for qualified borrowers. Lower down-payment options may include mortgage insurance or other costs. Ask a licensed lender to compare the available choices for your circumstances.
How much should I expect in closing costs?
The CFPB says closing costs often range from 2 to 5 percent of the purchase price, not including the down payment, but actual costs vary. Use the lender’s Loan Estimate for a transaction-specific projection.
Should I talk to a lender before contacting a real estate agent?
You may contact either professional first, but financing should be clarified before serious touring or making an offer. A good agent and lender can coordinate the early planning.
Do I need flood insurance if the lender doesn’t require it?
A lender’s requirement isn’t the same as a complete risk decision. Review the official flood zone, elevation information, insurance options, property history, and your own risk tolerance with qualified professionals.
Should a first-time buyer purchase a new-construction home?
New construction can be a strong option, but buyers should compare incentives, financing terms, lot and upgrade costs, future phases, HOA and CDD obligations, completion timing, inspections, warranties, and resale competition. The builder’s representative works for the builder.
Official homebuyer resources
- Consumer Financial Protection Bureau homebuyer tools
- CFPB Loan Estimate explainer
- U.S. Department of Housing and Urban Development homebuying guide
Build the plan before clicking through listings
Shawna Calvert and 27North Realty help first-time buyers understand the Tampa Bay and Southshore market before the search becomes overwhelming. The goal isn’t to push a buyer toward the maximum price. It’s to build a clear strategy, compare the full costs, and identify a home that works for the buyer’s life.
Thinking about buying your first home in Apollo Beach, Ruskin, Riverview, Wimauma, Gibsonton, Sun City Center, or the surrounding Tampa Bay area? Contact Shawna Calvert to begin with a practical buying plan. This article provides general information and isn’t legal, tax, insurance, or lending advice.